Yum! Brands
Global Leadership Meeting
Innovation and growth during the 2009 downturn: international expansion, changing consumer behaviour, mobile technology and brand innovation.
From clicks-and-mortar to anticipatory fulfillment.
For more than three decades, Jim Carroll has helped retailers, consumer brands, restaurants, grocers, distributors, packaging companies and supply-chain leaders understand how fast consumer behaviour changes - and how organizations must move with it.
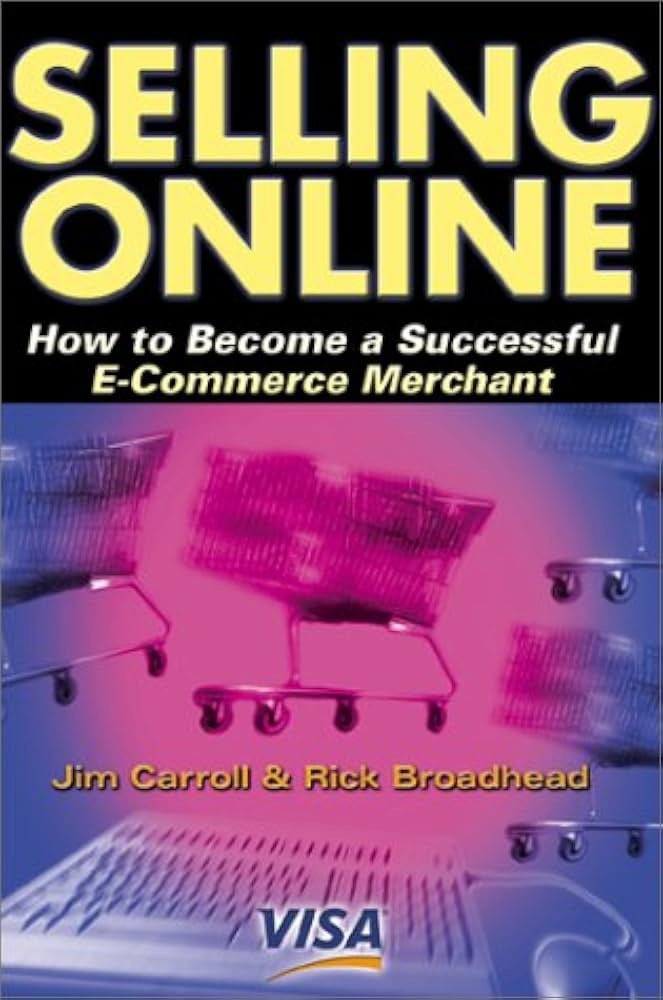
In 1999 Jim Carroll and Rick Broadhead published Selling Online: How to Become a Successful E-Commerce Merchant.
A senior executive at VISA USA saw the book and commissioned a custom edition of more than 60,000 copies, including VISA-specific content. VISA promoted and distributed the book to leading merchants as a practical guide to understanding the emerging world of online commerce.
Jim's message was deliberately pragmatic: pure-play “selling soap on the Web” hype was overdone. The larger revolution would come from B2B supply-chain restructuring and from digitally empowered customers using the Internet to influence physical-store purchases.
Product cycles shrink. Consumer tastes flip. New payment methods spread. Fulfillment expectations reset. A pacesetter changes the rules and everyone else has to catch up.
Behaviour, attention, trust, health, value, convenience and influence change faster than traditional planning cycles.
Move from committee-speed thinking to fast experimentation, rapid learning and disciplined scale.
Align the store, supply chain, data, pricing, payments and fulfillment around one continuous customer journey.
These are directions, not canned speeches. They are blended around the audience, channel, product category, brand and strategic agenda.
Fast consumers, intelligent commerce and relentless velocity.
Shopping agents, dynamic pricing, personalization and machine-mediated commerce.
How logistics, fulfillment and e-commerce redefine physical retail.
Attention, trust, health, influence, value and convenience.
Collapsing product cycles, packaging intelligence and supply-chain velocity.
Innovation, growth and organizational speed.
Jim's retail work began before most organizations had a serious e-commerce strategy.
E-commerce realism, empowered consumers, B2B supply chains and the first serious online merchant strategies.
E-grocery, B2B ordering, customer loyalty, packaging innovation, retail systems and supply-chain integration.
Mobile shopping, experience-driven stores, changing checkout, same-day delivery and store-as-showroom models.
Click-and-collect, voice commerce, intelligent packaging, dynamic pricing, last-mile logistics and relentless velocity.
Shopping agents, anticipatory fulfillment, machine customers, algorithmic merchandising and real-time personalization.
Jim was making this call more than a decade ago. By 2026, ship-from-store, click-and-collect, dark stores and micro-fulfillment have made it an operating model.
The physical store increasingly becomes one node in a much larger network of inventory, data, fulfillment, pickup, returns and experiences. The back end increasingly defines the front end.
Mobile payments, handheld checkout, tap-to-pay, digital wallets and cashierless formats turned payment from a place into a background process.
The phone did not simply become a shopping tool. It became the store interface.
Same-day delivery, next-day expectations, click-and-collect and ship-from-store changed what consumers define as fast.
The boring innovation - massive software-driven fulfillment infrastructure - mattered more than the photogenic innovation.
AI agents increasingly compare products, evaluate value, check availability, assemble baskets and make purchase decisions. Retailers must increasingly sell to both people and machines.
If the machine cannot find you, understand you, trust your data or verify your value, it can route around you.
Algorithms increasingly connect price, inventory, demand, competition, weather, location, loyalty and promotion in real time.
Prices become more responsive to context, demand and inventory.
Promotions become more relevant to actual behaviour and loyalty data.
Assortment and promotion decisions move closer to the moment of demand.
Active packaging, intelligent labels, connected products, sustainability, traceability and changing consumer expectations turn packaging into data, brand experience and logistics infrastructure.
Packaging stops being only a container. It becomes an information layer.
The structural shifts landed. Some of the most photogenic technologies took longer.
The Web transforms stores and supply chains rather than simply killing them.
The store becomes the front end for a logistics and e-commerce system.
The cash register disappears and the phone becomes the payment interface.
Same-day and omnichannel become competitive infrastructure.
Stores and malls evolve toward experience and logistics roles.
Global franchise systems, food and CPG companies, retailers, pricing companies, packaging organizations and supply-chain leaders.
Innovation and growth during the 2009 downturn: international expansion, changing consumer behaviour, mobile technology and brand innovation.
The changed consumer, retail acceleration and the new operating environment.
A senior executive group: end of inventory, consumer velocity, fulfillment and the trends reshaping the store.
Repeat global engagements in Europe focused on consumer behaviour, food trends, supply chain and retail transformation.
The challenge is not simply knowing what is changing. It is deciding what to do before the change becomes obvious.
Ten trends rocking retail, consumer fickleness, hyper-innovation and avoiding price commoditization.
Digital relevance, youth purchasing habits and adapting to a hyper-velocity consumer market.
Relentless velocity, consumer attention, real-time pricing and data-driven merchandising.
Different feedback, all pointing to relevance, research and impact.
“Absolutely stunning. We know that retail and consumer behaviour is changing fast, but you really put it into perspective with detailed insight - it's obvious you did your homework. The best speaker we have ever had!”Retail / Consumer Client Feedback
“We thought we needed good insight into how we might be impacted by rapid changes in the business environment and consumer behaviour. We got more than we bargained for - not only concise details on key trends, but workable action plans as well.”Client Leadership Feedback
“A stunning keynote with extremely powerful insight. Humour, energy, deep research and relevant content for our audience. We loved him!”Client Event Feedback
“You were superb! As we make changes your message could not have come at a better time. This group likes tradition but unfortunately that often gets in the way of moving forward.”Leadership Client Feedback
A grocery chain, luxury brand, restaurant franchise, packaging company and pricing platform do not face the same future.
Client calls, retail reports, consumer data, market research, current news, agenda analysis, category trends and sector-specific examples. No two presentations are the same.
LISTEN → RESEARCH → MAP THE TRENDS → BUILD THE STORY → CONNECT THE ROOM → LEAVE A PLAYBOOK
Retailers, global brands, restaurants, grocers, packaging, retail technology and supply-chain organizations.
Retailers & consumer brands: The GAP • Disney Retail • Godiva • Pladis • Nestlé • Loblaw • Shoppers Drug Mart • Canadian Tire • HMV • Save-On-Foods
Restaurants & franchise systems: Yum! Brands • Burger King • Subway • Multi-Unit Franchise Conference • Prime Restaurants
Grocery & convenience: Canadian Federation of Independent Grocers • Grocery Innovations Canada • FMI • National Association of Truck Stop Operators
Retail technology & value chain: Revionics • Retail Value Chain Federation • APICS • XCelerate • Ingram Micro • Grand & Toy • SAP Retail
Packaging & consumer products: PMMI • HAVI Global Solutions • Mondi • NatureWorks • TetraPak
Early e-commerce leadership: VISA USA • AIMS Online Retailing Summit • Retail Council of Canada • Canadian Retailer magazine.
Tell Jim who is in the room, what category you compete in and what is changing fastest around the customer.
Retailer? Brand? Grocery? Restaurant? Packaging? Retail technology?
AI, consumer behaviour, fulfillment, pricing, leadership or a blend.
Research, stakeholder calls, category trends and event integration.
Timing, format, fees, travel, logistics and the best next step.
Jim is always pleased to jump on a quick exploratory Zoom or phone call to learn more about the audience and talk through possibilities.
Contact JimGrab the PDF